USDA Loans Near Spring Hill, TN: How Address Eligibility Works
How address-by-address eligibility, income limits, and borrower requirements determine whether zero-down USDA financing is an option near Spring Hill — from a local broker.
Short answer: parts of the Spring Hill area may qualify for a USDA loan — but eligibility is determined address-by-address, and many addresses in the more developed parts of town do not qualify. If you've heard "Spring Hill isn't USDA anymore" or "Spring Hill is still USDA," the truth is both, depending on where the property sits. I'm Andrew Meyers, a licensed mortgage broker (NMLS #2320581) with Thrive Lending LLC, based next door in Thompson's Station, and I run this exact address check for buyers regularly.
Why Everyone's Confused About USDA in Spring Hill
USDA loans are meant for rural and less-developed areas, and eligibility maps are updated over time as population data changes. Spring Hill has grown quickly — it straddles the Williamson/Maury county line, and newer subdivisions have been built throughout the area. The result: areas that qualified in the past may not today, and some nearby addresses may still qualify — but only a check of the specific address can confirm it.
Two things matter here. First, USDA evaluates the exact property address, not the town name — a property on one side of a road can qualify while the other side doesn't. Second, how a map change affects a loan already in process depends on current USDA guidelines and timing, so that should be confirmed with your lender for your specific file rather than assumed.
Why Zero Down Can Matter for Spring Hill Buyers
Home prices in the Spring Hill area change over time and vary by neighborhood, so I won't quote figures here. The point is simple: a program that allows no down payment for eligible borrowers can meaningfully reduce the cash needed up front compared with programs that require a minimum down payment. USDA loans also use a guarantee fee structure rather than conventional private mortgage insurance; how the costs compare depends on the loan and the borrower. That's why I check USDA first when the address may allow it.
To be clear: zero down doesn't mean zero cash — you'll still have earnest money, inspection, and closing costs, though sellers can contribute toward those. And every approval is subject to underwriting.
Where to Look for USDA-Eligible Addresses Near Spring Hill
Buyers who want the Spring Hill lifestyle with USDA financing often start by looking at less-developed areas outside the city core and at the smaller communities a short drive out in Maury County. Some addresses around Thompson's Station may also be worth checking. No road, subdivision, or town is eligible as a whole — every property has to be verified individually against the current USDA map and guidelines. The commute is often still workable: Saturn Parkway and I-65 connect the area to major employers and Franklin offices.
USDA Basics: Do You Qualify?
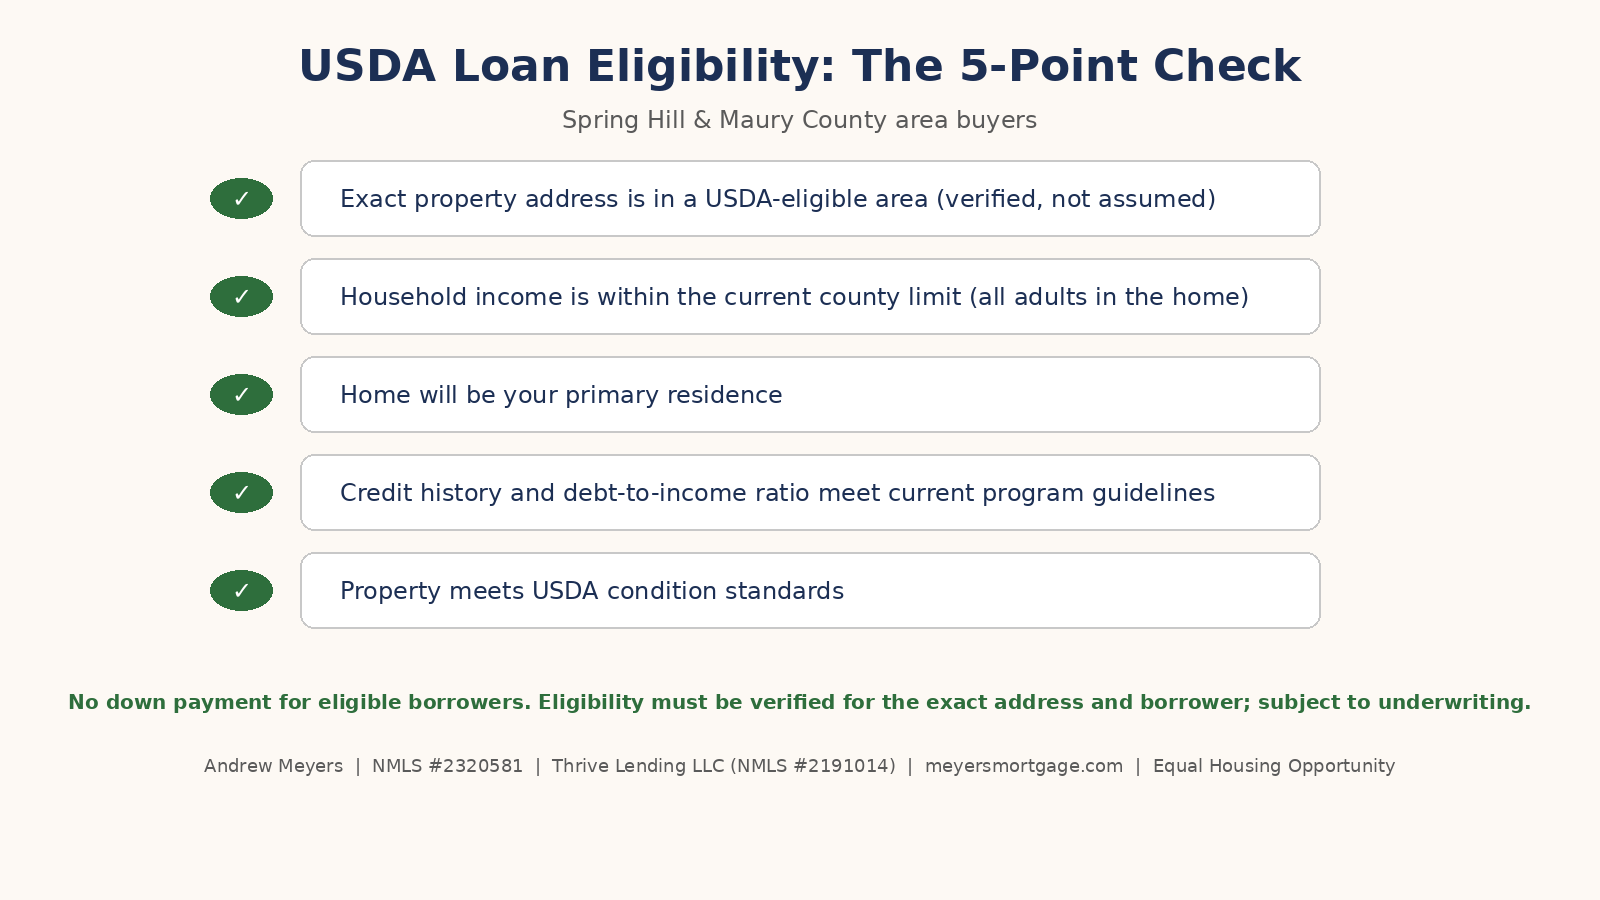
Beyond the address, USDA has borrower requirements:
- Income limits. Your household income must fall under the county limit, which varies by household size and is updated periodically — I can verify the current limit for your household. Note it counts household income, not just borrowers on the loan.
- Primary residence only. No investment properties or second homes.
- Credit and debt ratios. You'll need a credit history and debt-to-income ratio that meet current program and lender guidelines, which can change. There's no single score that guarantees approval.
- The property itself. Must be in an eligible area and meet USDA property standards.
How to Check Your Address (the Right Way)
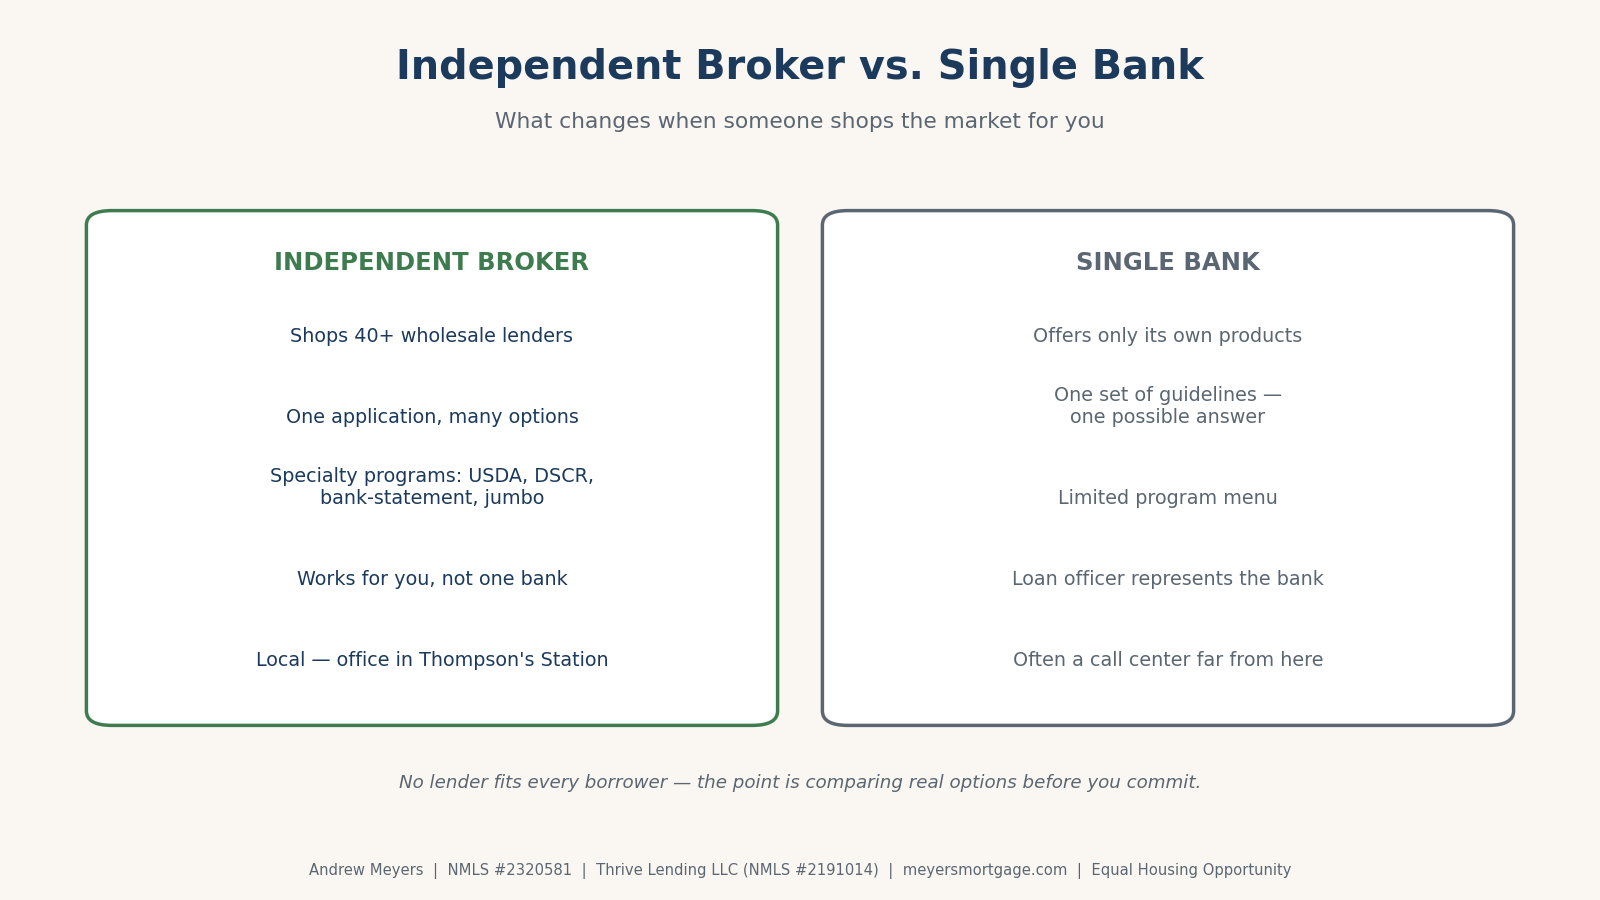
The USDA publishes a public eligibility map, but it's clunky and easy to misread — lot lines near boundaries trip people up constantly. A map result alone also doesn't guarantee approval — income, occupancy, borrower, and property requirements still apply. The better path: send me the address, and I'll verify eligibility and review your household income against the current county limits at the same time. No cost, no obligation. As an independent broker with access to 40+ wholesale lenders, I can also compare the USDA option side-by-side against FHA and conventional so you're choosing with a clear comparison.
FAQ: USDA Loans Around Spring Hill
Is Spring Hill itself USDA eligible?Not as a whole. Eligibility is determined by the exact address, and many addresses in the more developed parts of town do not qualify, while some others nearby may. Always verify the specific address against the current USDA map and guidelines.
What if the map changes while I'm under contract?It depends on current USDA guidelines and where your loan is in the process. Ask your lender how a pending map change would affect your specific file rather than assuming eligibility is locked in.
Is USDA only for farms?Not at all. It's a standard mortgage for regular homes — the property just has to be in a designated eligible area and meet program requirements. Many eligible homes are ordinary houses in established neighborhoods.
Can I make too much money for USDA?Yes — it's the one major program with household income caps. If you're over the limit, FHA or a low-down conventional loan may be the better fit, and I'll tell you which.
Check Your Address Today
If you're shopping in or around Spring Hill and want to know whether a USDA loan is on the table, reach out for a free, no-pressure eligibility check. Call or text (541) 632-0920, or start from my Spring Hill page.
Andrew Meyers, Licensed Mortgage Broker · NMLS #2320581 · Thrive Lending LLC (NMLS #2191014) · 2035 Tollgate Blvd, Thompson's Station, TN 37179 · Equal Housing Opportunity. All loans subject to underwriting, program guidelines, and USDA area/income eligibility; nothing here is a commitment to lend.