First-Time Home Buyer Programs in Columbia, TN
Down payment assistance, FHA, USDA, VA and low-down conventional options — explained in plain English by a Maury County mortgage broker.
If you're a first-time home buyer in Columbia, TN, you have more help available than most people realize. Between down payment assistance programs, FHA and USDA loans, and low-down-payment conventional options, eligible Maury County buyers may be able to buy with less cash up front than they expect. I'm Andrew Meyers, a licensed mortgage broker (NMLS #2320581) based just up the road in Thompson's Station, and helping first-time buyers in Columbia is a big part of what I do.
Here's what's actually available, in plain English.
Why Many First-Time Buyers Look at Columbia
Columbia is often one of the more accessible entry points to the Middle Tennessee market compared with some nearby Williamson County communities. Home prices change over time and vary by neighborhood and property, so any comparison should be based on current listings. For a first-time buyer, the purchase price shapes the down payment, the monthly payment, and how much cash is needed at closing.
And Columbia isn't a compromise. The downtown square and arts district keep getting better, the Duck River runs through town, and the commute up Highway 31 or I-65 to Spring Hill and Franklin jobs is manageable. With the GM and Ultium plants nearby in Spring Hill, a lot of my Columbia buyers work ten minutes from home.
Four Loan Programs Columbia First-Time Buyers Should Know
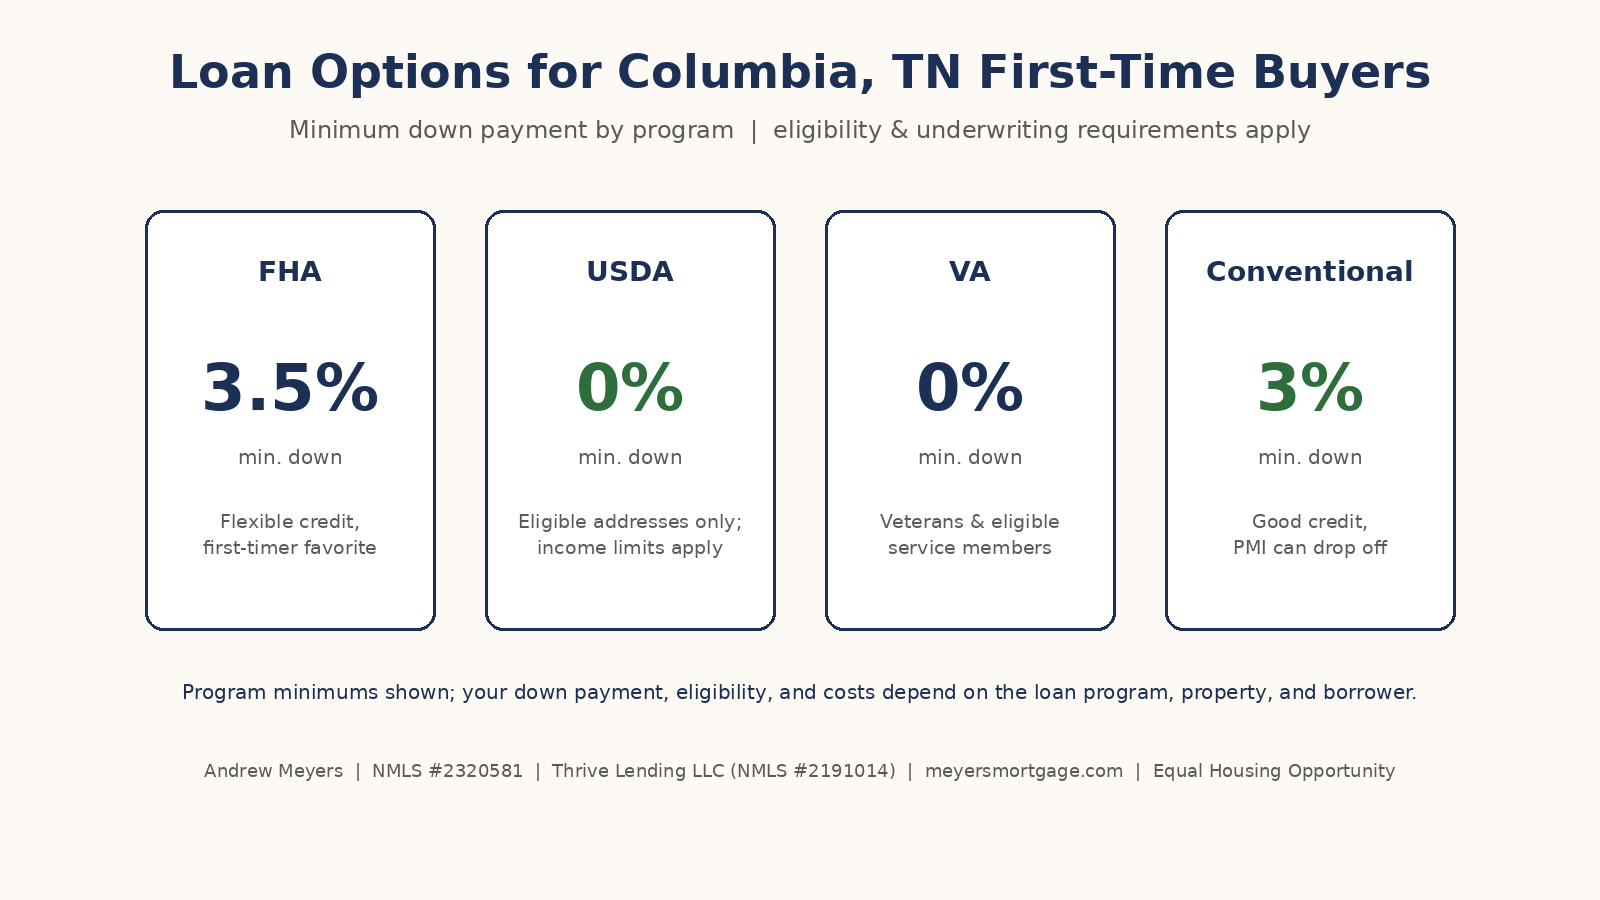
1. FHA Loans — 3.5% Down, Flexible Credit
FHA is a common starting point for first-time buyers. It allows a down payment as low as 3.5% for eligible borrowers and is generally more flexible on credit than many conventional loans. Down payment assistance (below) may help with part of that cost for qualifying buyers. FHA loan limits for Maury County are set annually, so the current limit should be confirmed before you shop.
2. USDA Loans — 0% Down for Eligible Addresses
Here's the one many buyers have never heard of: USDA loans can allow eligible borrowers to buy with no down payment. Eligibility is not based on the town name — it depends on the exact property address, household income limits, owner-occupancy, borrower eligibility, property requirements, and current USDA guidelines. Some addresses in and around Maury County may be eligible while nearby addresses are not, so every property has to be checked individually. If you're open to looking a little outside the city core, it's worth verifying the address before you rule USDA in or out.
3. VA Loans — 0% Down for Those Who Served
If you're a veteran, active-duty service member, or eligible surviving spouse, a VA loan may offer no down payment and no monthly mortgage insurance. Maury County has a strong veteran community, and in my experience VA buyers are often surprised how competitive their offer can be.
4. Conventional 97 — 3% Down with Good Credit
Conventional loans through Fannie Mae and Freddie Mac allow as little as 3% down for first-time buyers with solid credit. For buyers with scores in the higher ranges, this can work out well because mortgage insurance can eventually be removed — unlike FHA in most cases.
Don't Skip the Down Payment Help
Here's what most Columbia buyers never hear: there isn't just one down payment assistance program — there are multiple options, including grants, forgivable second loans, deferred seconds, and lender-funded assistance. Amounts, credit requirements, income limits, and purchase-price limits vary by program and can change. The right one depends on your cash, credit, and how long you plan to stay. I cover the options in detail in a separate guide.
What a Broker Does That a Bank Can't
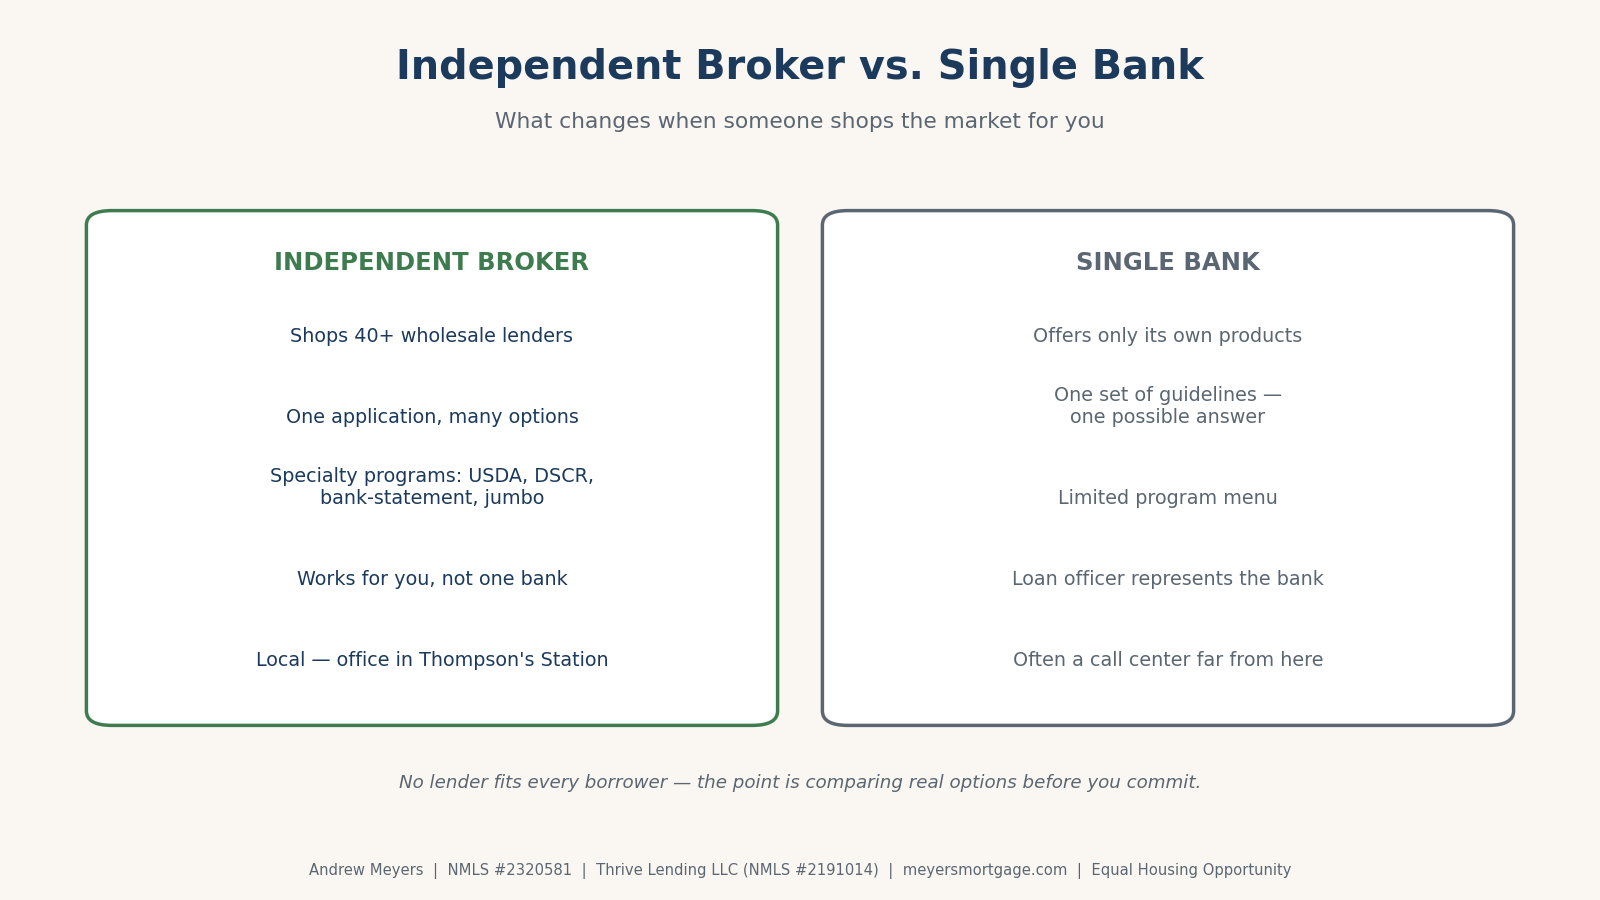
A single bank can only offer you its own products. As an independent broker with Thrive Lending LLC, I shop your file across 40+ wholesale lenders and match you with the program that fits — FHA, USDA, down payment assistance, conventional, whatever your situation calls for. For first-time buyers, that matters most when your file isn't cookie-cutter: newer credit, self-employment income, or a tight budget where every dollar of closing cost counts.
FAQ: First-Time Buying in Columbia
How much do I really need saved to buy in Columbia?It depends on the program, the purchase price, and your situation. Between low-down-payment programs and down payment assistance, some eligible buyers bring less cash to closing than they expected, though earnest money, inspection, appraisal, and closing costs still need to be planned for. Every file is different and subject to qualification and underwriting.
What credit score do I need?There's no single magic number. FHA can work with lower scores than conventional, and assistance programs set their own minimums, which vary by program and can change. If your score needs work, I can point you to what actually moves it before you apply.
Is now a good time to buy in Columbia?I can't predict rates or prices. The right time is when your budget and life are ready — a free eligibility check tells you where you stand.
Do I have to be a first-time buyer for these programs?Not always. USDA and VA have no first-time requirement, and many assistance programs count you as "first-time" if you haven't owned a home in the past three years.
Can first-time buyers combine down payment assistance with a mortgage?Some assistance programs may be paired with eligible first-mortgage programs. Compatibility, income limits, purchase-price limits, property rules, repayment terms, and lender participation vary. The combination must be reviewed for the specific borrower and property scenario.
Let's Find Your Program
If you're thinking about buying your first home in Columbia, let's have a no-pressure conversation about which first-time home buyer program fits you. The eligibility check is free and there's no obligation. Call or text me at (541) 632-0920, or reach out through my Columbia page.
Andrew Meyers, Licensed Mortgage Broker · NMLS #2320581 · Thrive Lending LLC (NMLS #2191014) · 2035 Tollgate Blvd, Thompson's Station, TN 37179 · Equal Housing Opportunity. All loan approvals subject to underwriting and program guidelines; nothing here is a commitment to lend.