DSCR Loans in Nashville & Middle Tennessee: The Investor's Guide
Nashville's growth has pushed real estate investors well past the city limits — into Spring Hill, Columbia, Franklin, and the smaller towns around Maury County where rents are climbing and purchase prices haven't caught up yet.
DSCR stands for debt-service coverage ratio — essentially, does the property's rent cover its own mortgage payment? Instead of underwriting your personal income with tax returns and pay stubs, the lender underwrites the property: they look at the rent it generates (or could generate, based on a market rent analysis) against the monthly mortgage payment. That single shift is what makes this program so useful for investors, especially ones who are self-employed, hold income across multiple entities, or simply don't want their personal tax returns driving the underwriting decision.
Why Middle Tennessee investors lean on this program
- No tax returns or W-2s required — the property carries the file, not your personal income documentation.
- Works for long-term rentals and, with many lenders, short-term rentals (Airbnb/VRBO) — relevant given how active the short-term rental market is around Nashville, Franklin, and Columbia.
- Scales with a portfolio. Because qualification is property-by-property rather than tied to your personal debt-to-income ratio, investors adding a second, third, or tenth door often find DSCR loans easier to stack than conventional investment financing.
- Closes on an LLC in many cases, which matters for investors who hold property for liability or estate-planning reasons.
What lenders typically look at
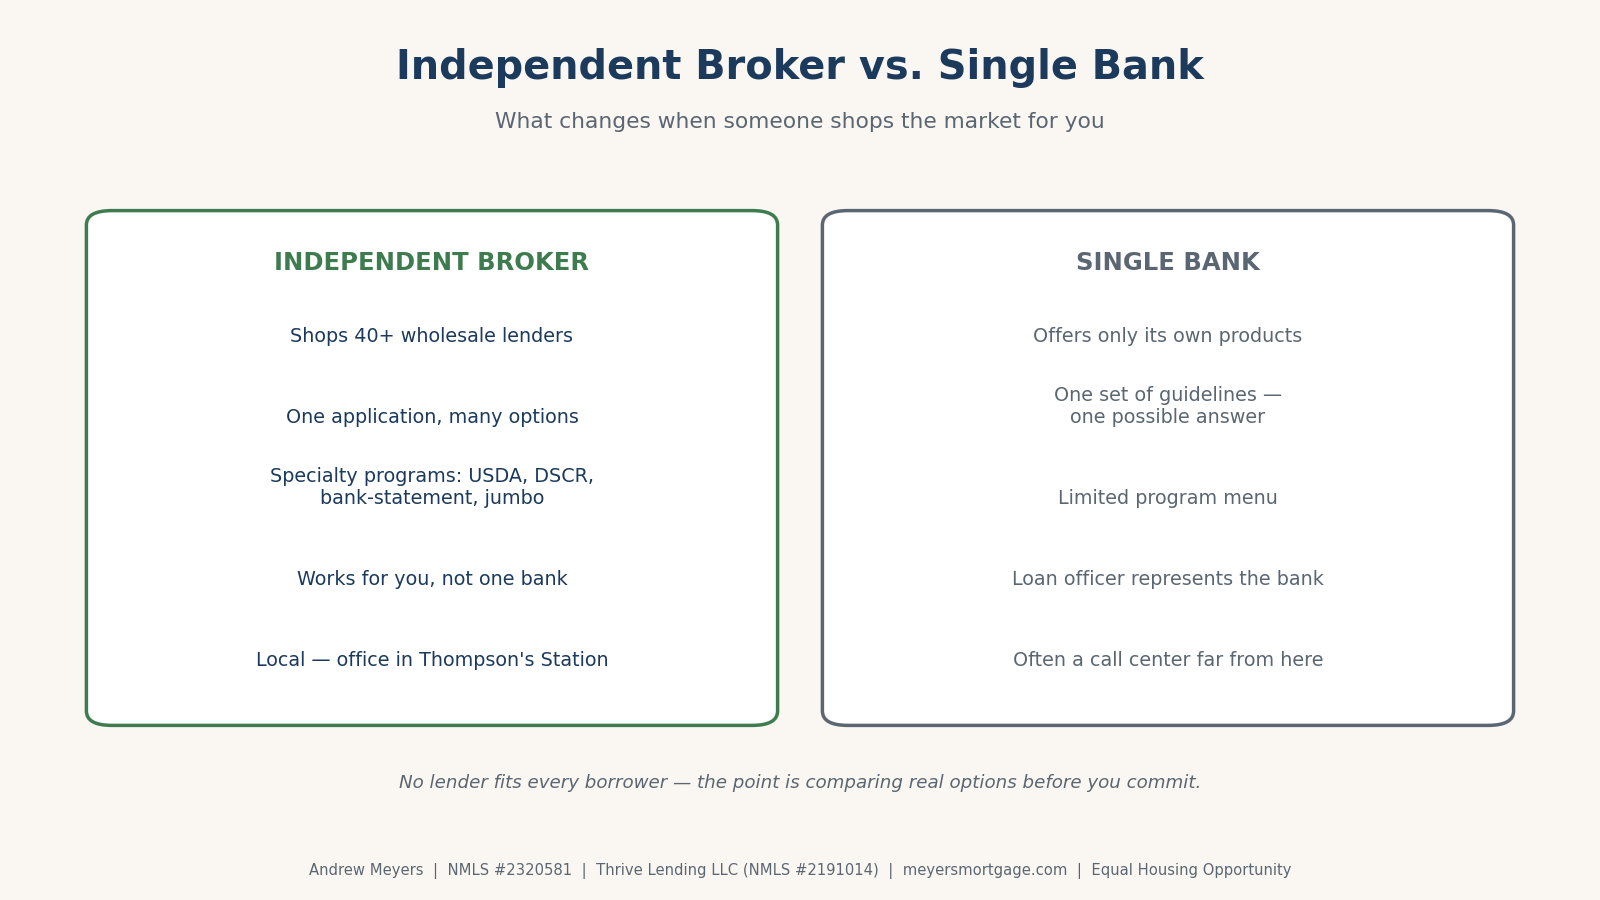
Every lender's DSCR program is a little different, but the core factors are consistent: your credit score, the down payment you're bringing, and the property's rent-to-payment ratio (its DSCR). Some programs will still approve a file where the rent doesn't fully cover the payment, just on different terms. Because I work across more than 40 wholesale lenders rather than one bank's single rulebook, I can usually find a program that fits a specific property and investor profile rather than forcing the deal into one lender's box.
Where this program fits in the Middle Tennessee market
Maury County — Columbia and the towns around it — has been one of the more active areas for investors chasing cash flow that's harder to find closer to Nashville. Spring Hill sits in the middle of that growth, with strong rent demand from people commuting toward both Nashville and the Maury County job base. Franklin and Williamson County trade at a higher price point, but rents and short-term rental performance there can still make the numbers work for the right property. Wherever you're looking, the underlying question is the same: does the rent support the loan, and does the program fit how you hold the property. If you're buying a primary residence rather than a rental out here, many of those same rural communities qualify for zero-down USDA financing — see my guide to USDA-eligible areas in Maury County.
Frequently asked questions
Do I need to be a full-time investor to use a DSCR loan?
No — DSCR loans are used by first-time investors buying a single rental just as often as by investors scaling a larger portfolio.
Is a DSCR loan more expensive than a conventional investment property loan?
Terms vary by lender and by how strong the property's rent-to-payment ratio is. I'll walk you through real numbers for your specific property so you can compare it against conventional financing directly.
Can I refinance an existing rental into a DSCR loan?
Yes — investors do this to pull cash out for the next purchase, or simply to get out from under personal-income underwriting on a property they already hold.
Ready to see what a DSCR loan looks like for your next property, or one you already own? Call or text (541) 632-0920, or email ameyers@thrivelending.us. Based at 2035 Tollgate Blvd, Thompson's Station, TN — serving investors across Nashville, Franklin, Spring Hill, Columbia, and all of Middle Tennessee.
Andrew Meyers, Licensed Mortgage Broker, NMLS #2320581 · Thrive Lending LLC, NMLS #2191014 · Equal Housing Opportunity. This is general information, not a commitment to lend, and not a guarantee of rate, terms, or approval.