USDA Eligible Areas in Maury County, TN: Where You Can Still Buy with Zero Down
USDA property eligibility varies by exact address and can change as program maps are updated. Property eligibility alone is not loan approval: household income, occupancy, credit, property condition, and current USDA and lender requirements also apply. I can check a specific address and household scenario before you rely on USDA financing.

USDA property eligibility is determined by the exact address, not simply by a city name or mailing address. Boundaries can divide nearby properties and may change when USDA updates its maps. Some properties outside the more densely developed portions of Columbia and Spring Hill may be eligible, including properties in and around smaller Maury County communities. Property eligibility alone is not loan approval: household income, occupancy, credit, property condition, and current USDA and lender requirements also apply.
HOW USDA PROPERTY ELIGIBILITY WORKS IN MAURY COUNTY
USDA uses an address-level property eligibility map. Homes in more densely developed areas are less likely to qualify, while some properties farther from those areas may qualify. A Columbia or Spring Hill mailing address does not by itself determine eligibility. Always verify the exact property using the current official USDA eligibility map before making an offer or relying on USDA financing.
COMMUNITIES BUYERS OFTEN ASK ABOUT
Buyers commonly ask about properties near Culleoka, Santa Fe, Mount Pleasant, Hampshire, Williamsport, and the less densely developed edges of Columbia and Spring Hill. These community names are useful search areas, but none is proof that a particular home qualifies. Each address must be checked individually.
WHAT ZERO DOWN ACTUALLY MEANS
USDA guaranteed loans may permit an eligible borrower to finance an eligible primary residence without a down payment. Zero down does not necessarily mean zero cash needed. Closing costs, prepaid taxes and insurance, inspections, appraisal expenses, guarantee fees, and other costs may still apply. Seller or lender credits may be available in some transactions, subject to the contract, appraisal, program limits, and lender guidelines.
HOUSEHOLD INCOME AND BORROWER ELIGIBILITY
USDA guaranteed loans apply household-income limits, which may include income from household members who are not borrowers. Limits vary by household size and location and are updated periodically. Credit history, debts, income documentation, occupancy, and lender requirements also matter. No single credit score, income amount, or address guarantees approval.
If USDA does not fit, an eligible buyer may still compare FHA, VA, conventional, or applicable down-payment-assistance options. The most suitable option depends on the borrower, property, occupancy, available funds, and current guidelines.
WHY VERIFY THE ADDRESS BEFORE MAKING AN OFFER
An early address review can help prevent a buyer from relying on a program that does not fit the property. I can check the address using the current USDA map, review the household-income framework, and compare available USDA, FHA, VA, and conventional structures. A preliminary review is not a commitment to lend and does not replace underwriting or property approval.
PROPERTIES WITH LAND AND NEW CONSTRUCTION
Potential eligibility for a property with land depends on the residential use, value allocation, condition, appraisal, and current USDA and lender guidelines. Working farms, income-producing property, and properties with certain nonresidential characteristics may not qualify. Acreage alone does not establish eligibility.
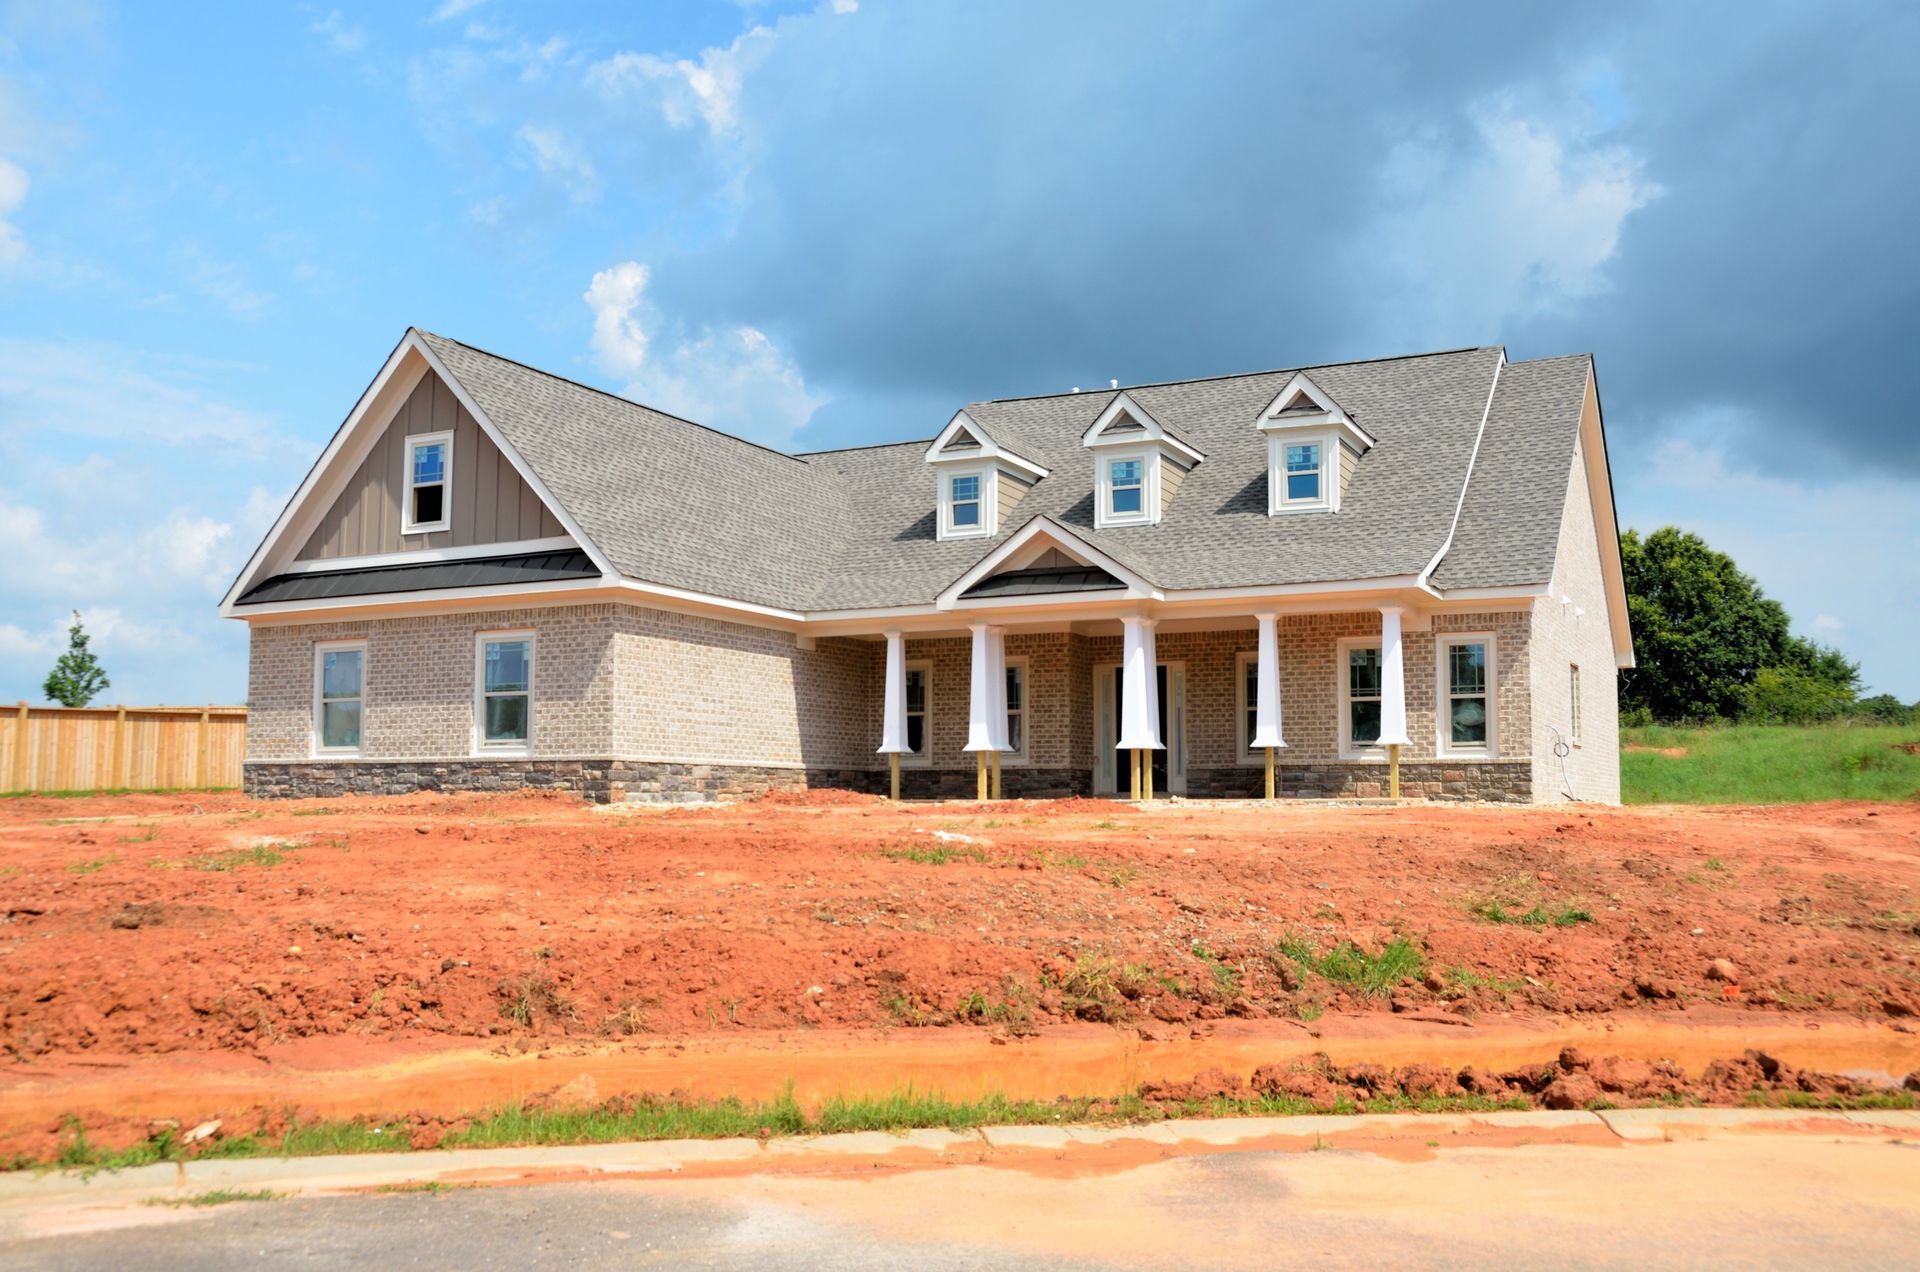
Some new-construction transactions may be eligible when the borrower, property, builder, documentation, and transaction satisfy current USDA and lender requirements. Confirm both the exact address and the construction scenario before relying on this option.
COMPARING USDA WITH FHA OR CONVENTIONAL FINANCING
Compare the estimated cash needed at closing, complete monthly payment, mortgage or guarantee fees, available credits, property requirements, and long-term costs using the same borrower and property information. Rates and pricing change, and no program is best for every buyer. A written side-by-side estimate is more useful than a broad claim that one program is always cheaper.
FREQUENT QUESTIONS
Can a property with a Columbia mailing address qualify? Possibly. The exact mapped address controls property eligibility, not the mailing city alone.
Do I need perfect credit? No single score guarantees eligibility or approval. The complete credit profile and application must be reviewed under current requirements.
Can I finance a property with land? Possibly, depending on its residential use, property characteristics, appraisal, and current requirements.
Can new construction qualify? Some transactions may qualify when all borrower, property, builder, and documentation requirements are satisfied.
How do I know whether USDA is the right option? Verify the address and household scenario, then compare the complete estimated costs and requirements with other available programs.
CHECK A MAURY COUNTY ADDRESS
If you are considering a home in Maury County, send me the exact property address and basic household information. I can help review whether USDA may be worth exploring and compare it with other available mortgage options. Call or text (541) 632-0920.
Andrew Meyers, Licensed Mortgage Broker · NMLS #2320581 · Thrive Lending LLC (NMLS #2191014) · 2035 Tollgate Blvd, Thompson's Station, TN 37179 · Equal Housing Opportunity. USDA eligibility is determined under current USDA Rural Development requirements. All loans are subject to qualification, property review, and underwriting. Not a commitment to lend.