A Mortgage Broker in Columbia, TN — What Local Buyers Should Know
A local broker's plain-English guide to buying in Maury County — loan options, down payment help, and how to get in with little cash.
Columbia is one of the fastest-changing housing markets in Maury County — close enough to Nashville for the commute, still carrying its own small-town identity, and priced well below Williamson County next door. If you're buying (or refinancing) here, the biggest decision you'll make before you ever pick a house is who you borrow from.
Why That Decision Matters More in Columbia
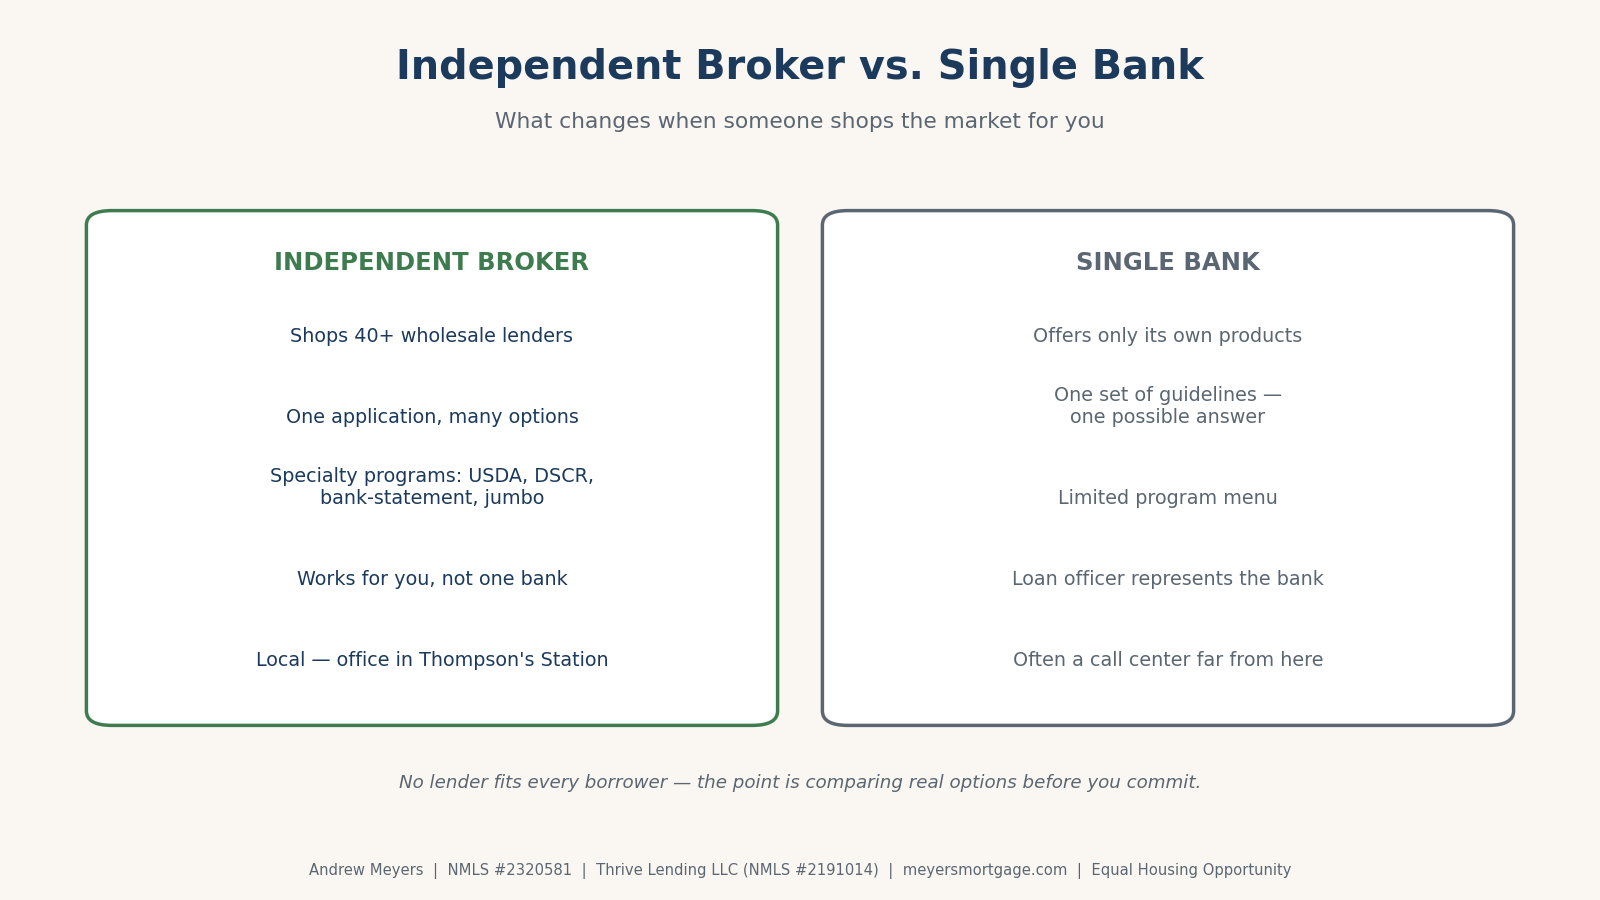
Most buyers walk into their bank first, because it's the name they know. The problem: a bank can only offer you that bank's own loan programs. An independent mortgage broker works differently — I shop your loan across more than 40 wholesale lenders and match you to whichever one actually fits your situation, whether that's a first-time buyer program, a USDA zero-down loan, or a bank-statement loan for a self-employed borrower. You get one point of contact and side-by-side pricing, instead of one offer.
I'm Andrew Meyers, a licensed mortgage broker (NMLS #2320581) based just up the road in Thompson's Station, operating under Thrive Lending LLC (NMLS #2191014). Columbia is one of my core markets — not an afterthought.
Columbia's Market, in Plain Numbers
As of Zillow's most recent data, the average home value in Columbia sits around $377,631, up roughly 1.2% over the past year, with a median sale price near $350,917 and homes typically going pending in about 33 days. That's meaningfully below neighboring Williamson County, which is a big part of why first-time buyers and move-up buyers are looking here. (These figures move month to month — treat them as a snapshot, not a quote, and I'll pull current numbers for your specific search.)
Loan Programs Columbia Buyers Actually Use
- USDA (zero down). A large share of Maury County — including many areas around Columbia — qualifies for USDA financing, though eligibility is parcel-by-parcel, not by mailing address. If you're not sure whether a specific property qualifies, see my full USDA Eligible Areas in Maury County guide or just send me the address.
- FHA. A common fit for first-time buyers with less than 20% down.
- Conventional. Often the better math once you're above roughly 20% down or have strong credit.
- Down payment assistance. Several programs apply to Columbia and Maury County buyers who assume they need more cash up front than they actually do — see Down Payment Assistance in Maury County.
- Bank-statement loans. Common in Maury County given the number of self-employed and small-business borrowers — qualifies off bank deposits instead of tax-return net income.
- DSCR loans. For investors buying rental property here, qualification is based on the property's rental income rather than your personal income.
Frequently Asked Questions
Do I have to be a first-time buyer to work with you? No — I work with first-time buyers, move-up buyers, refinances, and investors across Columbia and Maury County.
Is my specific Columbia property USDA-eligible? Possibly — eligibility is determined parcel-by-parcel. Areas inside Columbia's city limits generally don't qualify, but a lot of the surrounding county does. Send me the address and I'll check it for you at no cost.
How is working with a broker different from going straight to my bank? A bank can only offer its own products. As a broker, I compare your loan across 40+ wholesale lenders and bring you the pricing and program that actually fits — not just whatever one institution has on the shelf that week.
What's the fastest way to know what I can afford? Start with a pre-approval — it takes a short conversation about income, credit, and goals, and gives you a real number to shop with. See how the process works start to finish.
Ready to Talk About Your Columbia Purchase or Refinance?
Call or text (541) 632-0920, or email ameyers@thrivelending.us. Based at 2035 Tollgate Blvd, Thompson's Station, TN — serving Columbia and all of Maury County.
Andrew Meyers, Licensed Mortgage Broker, NMLS #2320581 · Thrive Lending LLC, NMLS #2191014 · Equal Housing Opportunity. This is general information, not a commitment to lend, and not a guarantee of rate, terms, or approval.